

A $1.3 billion apartment loan reached maturity after the portfolio shrank from 21 properties to six. The remaining buildings reportedly generated more cash flow than underwritten. The apartments are working. The debt is not.
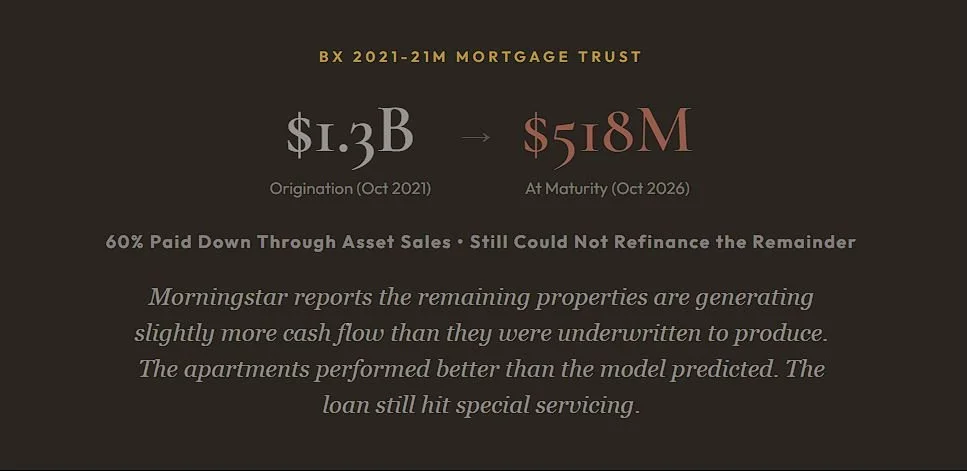
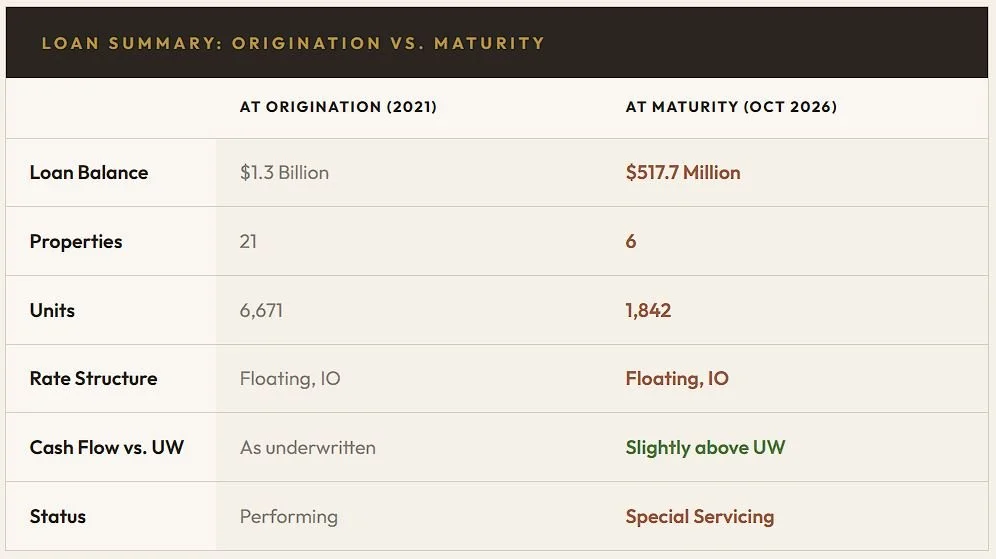
A $1.3 billion CMBS loan originated in October 2021 by Barclays and Morgan Stanley, backed by 21 multifamily properties totaling 6,671 units across Texas, Florida, Georgia, and Seattle, entered special servicing after missing its October 2026 maturity date. The borrower is Blackstone Real Estate Partners IX.
Blackstone has been selling properties to pay down the loan since at least 2023. Fifteen of the 21 properties have been sold, each at a release premium of 105% to 110%. The remaining balance is $517.7 million, secured by six properties and 1,842 units. Blackstone received a three-month forbearance to sell the rest.
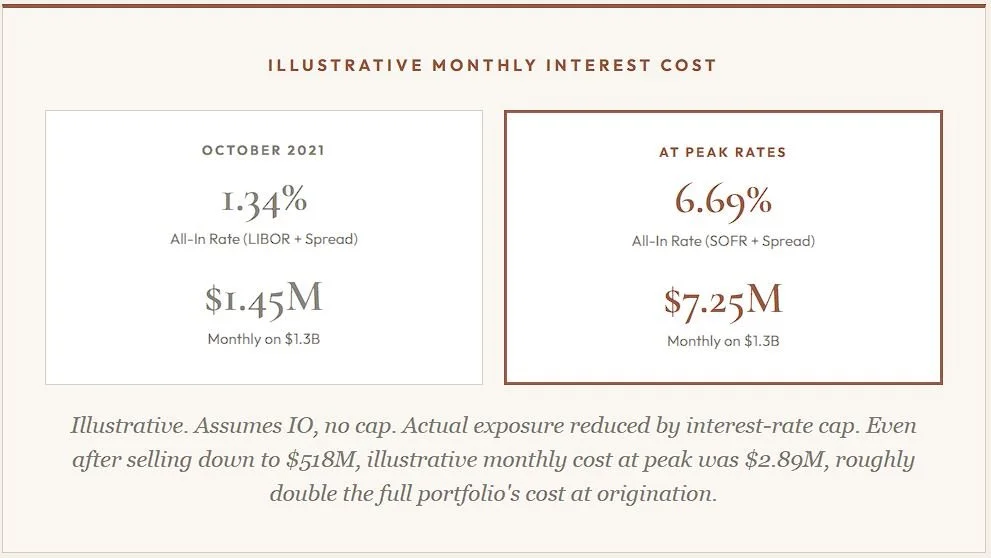
A Fivefold Increase on the Same Portfolio
“The apartments performed better than the model predicted, and the loan still hit special servicing. If that does not separate the asset question from the capital-structure question, nothing will.”
The $757 Billion Maturity Wall Has a Name Attached
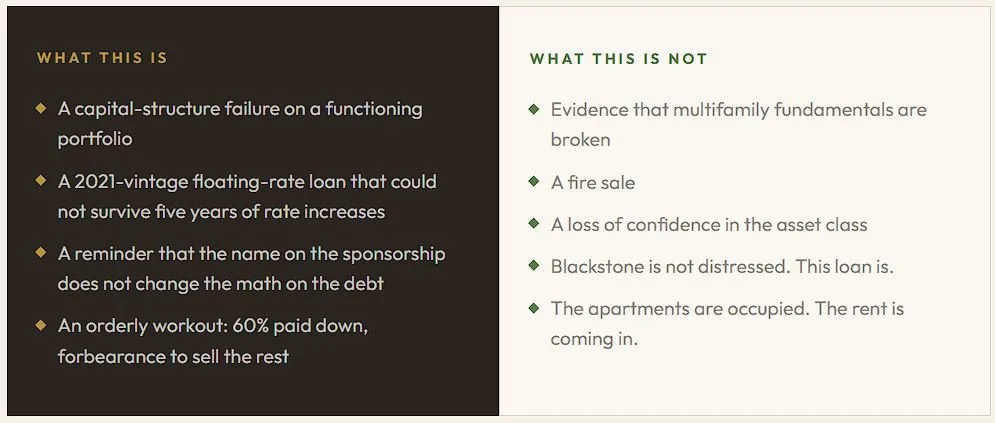
When a Blackstone fund with access to unlimited institutional capital, best-in-class asset management, and a five-year head start on selling down the portfolio still cannot fully resolve a 2021-vintage floating-rate loan at maturity, the problem is structural, not operational.
The multifamily CMBS special servicing rate rose to 8.54% in September. Multifamily accounts for 51.86% of the severely impaired CMBS balance nationally. In Texas, troubled loans tied to properties flagged for foreclosure topped $1 billion for the fourth time in 2026. The NMHC Multifamily Debt Financing Index plunged to 10, its lowest reading on record.
On Blackstone's own Q3 earnings call, President Jon Gray acknowledged that rates had an impact particularly on slower-growing assets, multifamily in the U.S. He also noted the supply tailwind: the fall-off in new multifamily starts from three years ago is now showing up. Vacancy is falling. Absorption is rising. The fundamentals are improving. The capital structures originated in 2021 at floating rates cannot wait for them.
Three Variables That Shape What Happens Next
-
Whether Blackstone completes the remaining sales within the three-month window. A clean resolution confirms orderly deleveraging. A failure to sell signals deeper pricing challenges even for institutional-quality assets.
-
Trepp reports heavy multifamily maturity volume through year-end. Each resolution reveals market pricing and refinancing conditions in real time.
-
If more properties enter special servicing despite performing above underwriting, the maturity wall thesis is confirmed at the institutional level, not just among syndicators.
“The asset and the financing are not the same investment. Underwrite both.
The barbell holds.”
Sources: Morningstar Credit (Oct 19, 2026); Commercial Observer; Multifamily Dive; Bisnow; Trepp; NMHC; Blackstone Q3 2026 earnings; ICE Benchmark Administration; CME Group. This material is for informational purposes only. Not investment advice.